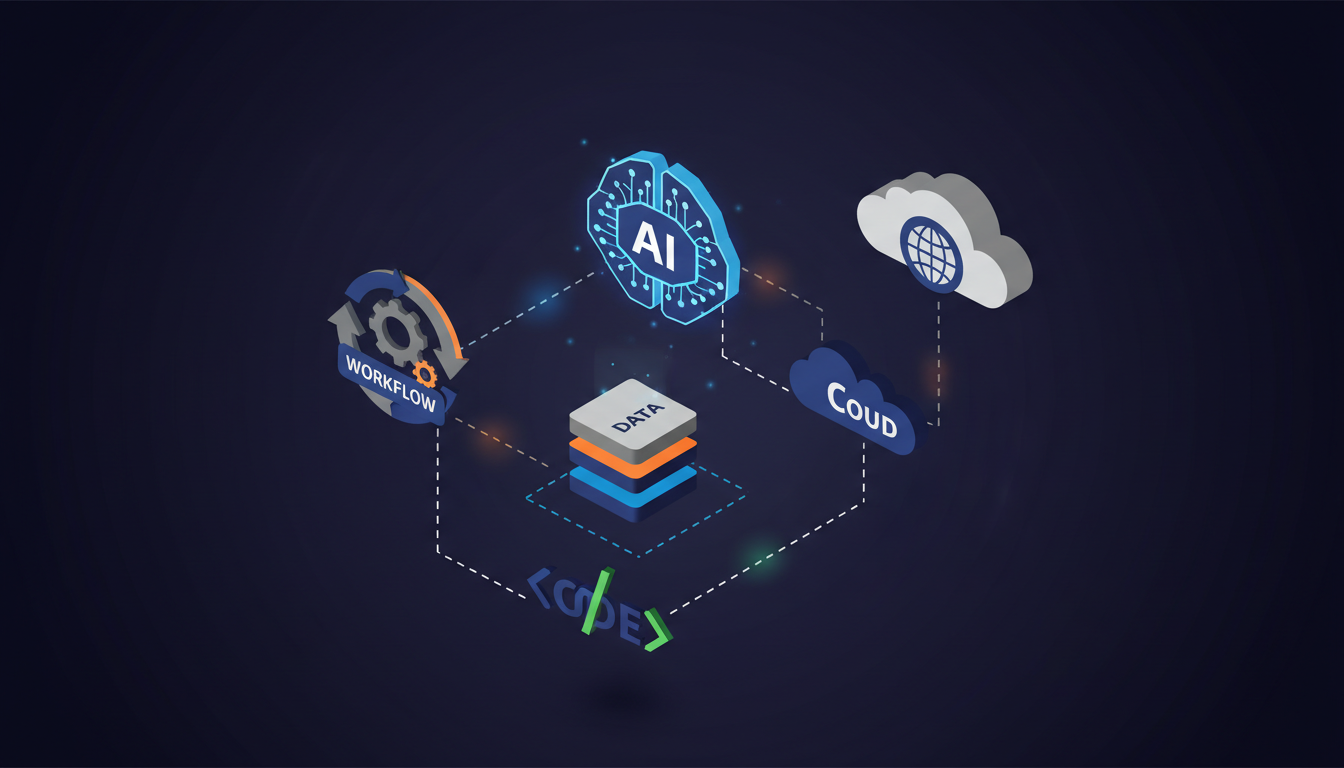

Digital transformation in enterprises rarely stalls due to lack of technology. It stalls due to insufficient velocity and governance combined. Organizations accelerating time-to-market without sacrificing compliance no longer bet on a single approach: they stack low-code and intelligent automation. This combination reshapes deployment timelines and operational business models, particularly in regulated sectors such as insurance.
The debate between these two paradigms is poorly framed. They are not alternatives but stages of the same rocket. Low-code builds the application infrastructure; intelligent automation makes it capable of real-time decision-making and adaptation.
Low-code is a development paradigm that minimizes manual programming in favor of visual components, modular assembly, and intuitive graphical interfaces. Developers and business analysts collaborate on the same platform without waiting for translation between technical languages and business requirements.
Core characteristics include:
OutSystems exemplifies the mature model: drag-and-drop workflow construction, automatic versioning, and guaranteed maintainability for complex applications. The result is measurable: time-to-market reduction of 40 to 60% compared to traditional development.
Intelligent automation merges Robotic Process Automation (RPA), Business Process Management (BPM), and Machine Learning. It orchestrates workflows, validates business decisions against compliance rules, and adapts application behavior contextually. Unlike basic automation executing predefined scripts, intelligent automation learns and adjusts.
Essential components include:
Low-code shortens cycles through parallelization. Business and technical teams work simultaneously rather than in relay. A business feature no longer requires three round-trips but one direct visual iteration.
Intelligent automation removes redundant application code layers intended for validation, routing, and data transformation. The decision engine handles these tasks.
Low-code provides design traceability: each component is explicit, dependencies visual, and modification impact observable. For regulated sectors, this architectural transparency reduces post-implementation audit phases.
Intelligent automation embeds compliance in execution, not downstream. Business rules, regulatory thresholds, and business validations execute step-by-step with exhaustive traceability. In insurance, this means every underwriting decision, claim, or tariff adjustment leaves an incontestable audit trail.
Extending a low-code application to a new geography means instantiating variants, then adding local specifics. Unlike monolithic code, each market can diverge without combinatorial explosion.
Intelligent automation enables each geographic instance to make decisions according to its regulatory context without recoding. Business rules are parameterized, not coded.
Low-code expands contributor scope. Business analysts, domain experts, and compliance officers can directly participate in construction. This creates stronger business ownership and reduces IT-business misunderstandings.
Intelligent automation transfers decision rule ownership to the business. Actuaries, underwriters, and compliance officers define rules directly in the engine without intermediary developers.
Low-code forces description of all paths: normal, exceptional, escalation. This exhaustiveness prevents dead ends and guarantees no cases remain suspended. Yet it creates visual complexity as scenarios multiply.
Intelligent automation handles exceptions through parameterized rules. An atypical insurance claim doesn't create a new code branch but contextual evaluation routing to the appropriate service. The engine adapts without application modification.
A low-code application costs less to maintain than a traditional one. Security updates are platform-managed, business evolutions coded visually without classical technical debt. According to NIST (2022), maintenance costs drop 40 to 50%.
Intelligent automation decreases operational costs by eliminating manual or semi-manual steps. In insurance, this means removing validation, routing, and manual traceability steps. WEF (2023) estimates this reduction between 30 and 50% depending on sector.